- Tax-free growth and withdrawals
- Control over future tax exposure
- Efficient conversion pricing
- Simplified estate planning
Why Should You Consider a Roth IRA Conversion?
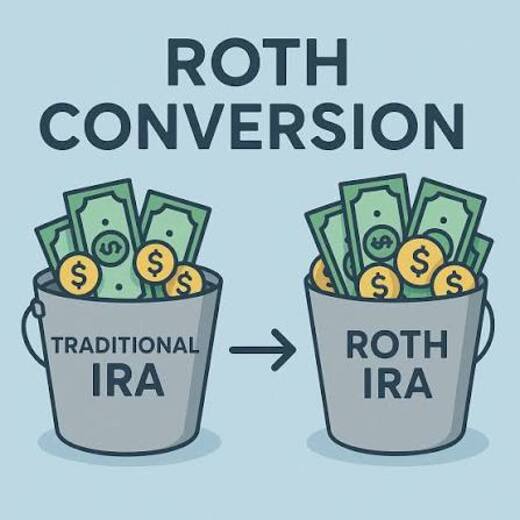
Explore the pros and cons of using an IRA Rollover to move money from your Traditional IRA to a Roth account.
Does converting make sense?
For many individuals, converting to a Roth IRA may make sense. However, you should consult with a tax advisor and consider the following factors prior to making your decision:
-
- Can you pay the taxes? – This is the big question for most folks. The amount you choose to convert (you don’t have to convert the entire account) will be taxed as ordinary income in the year you convert. So, you’ll need to have enough cash saved to pay the taxes on the amount you convert. Keep in mind: This additional income could also push you into a higher marginal federal income tax bracket.
- Is time on your side? – The relative benefits of conversion will generally increase the longer your money remains in the Roth IRA. Specifically, if you need that money in less than 5 years, converting is generally not a good idea. If you’re age 50 or older, learn more in our Viewpoints article on Roth conversions specifically addressing your considerations.
- Will you earn the same or more in retirement? – If you think your tax rate will be the same or higher in retirement, converting now could make sense. Why? Because Roth IRAs do not have required minimum distributions (RMDs) during the lifetime of the original owner. That means you could convert now and just keep giving the money a chance to grow, untaxed, without withdrawing. (Keep in mind: If you are required to take an RMD in the year you convert to a Roth IRA, you must do so before converting.)
- Do any of these other scenarios apply to you?
- You think the value of your IRA investments is hitting a low point.
- You have other losses or deductions to offset the tax due on the conversion.
- You are moving to a state with higher income taxes.
If so, a conversion may also make sense for you.
Meet Your Wealth Managers
“Continuity should be one of the main factors when you look into investing with a financial advisor or wealth manager.”
Sander Read
President & Chief Executive Officer
31 Years Managing Wealth
“The big hurdle is the lack of support for recovering passwords, keys, and digital asset locations, making pre-planning crucial.”
Corey Roun
Sr. Director of Trading & Derivatives Strategies
15 Years with Lyons Wealth
“We have a fiduciary duty to always put clients’ interests first, we only do better, when you do better.”
Matt Ferratusco
Senior Portfolio Manager & Analyst
9 Years with Lyons Wealth
“Small-cap stocks offer big growth potential—we help you seize those opportunities with confidence and precision.”
Mark Zavanelli
Senior Portfolio Manager
5 Years with Lyons Wealth
Who We Work With
At Lyons Wealth, we get to know our clients to understand their specific goals, objectives, needs, and future desires. We look for a good fit for everyone involved and want to engage in long-term relationships with the clients we advise. Our client roster ranges from:
- Multi-Generational Wealthy Families
- Corporate Executives with Concentrated Stock Holdings
- Successful Individuals
- Business Owners
- Fiduciaries of Charitable Funds
- Investment Professionals
“Working with Lyons has been amazing. The team is professional and communicative so I always know how my investments are doing.”
Daniel S
Business Owner
“Lyons Wealth Management helped educate me and allay my fears, as well as provided solid guidance on steps I could take to help me reach my goals even sooner.”
Dorothy P
Successful Individual
Start Investing With Lyons Wealth Today!
Schedule a call with a financial advisor to discuss the best strategy for you!
Disclaimer:
Past performance does not guarantee future results.
Subsequent markets may perform better or worse than for the periods shown, which will cause the actual results of a portfolio to be better or worse than shown. LIM does not guarantee or offer any assurance that any portfolio or account will be profitable, meet a client’s stated objectives, or prevent or reduce losses. A client may lose money by investing in a portfolio. Actual realized returns will depend on, among other factors, the value of assets and market conditions at the time of disposition, any related transaction costs, and the timing of the purchase. This is not a recommendation nor an offer to sell (or solicitation of an offer to buy) securities in the United States or in any other jurisdiction.
The Fundamental Small Cap Value Composite consists of accounts that hold U.S. small cap stocks selected by using LIM Fundamental Analysis. This analysis identifies undervalued companies using LIM’s GRAPES valuation model and applies other selection criteria relating to a company’s business prospects, management quality, and capital structure. The benchmark for the composite is the Russell 2000 Index, presented in U.S. Dollars. The Russell 2000 is a market cap weighted index of small company US stocks. In the past the composite has displayed higher volatility than its benchmark. Investing in small capitalization companies generally involves greater risk than investing in larger, more established companies. The S&P 500 is a market-capitalization weighted index of 500 leading publicly traded companies in the U.S.
The composite includes fully discretionary, management fee-paying and, beginning on January 1, 2011, non-management fee-paying accounts, including those accounts no longer with the firm. The U.S. Dollar is the currency used to express performance. Returns are presented net of management fees and include all trading expenses and the reinvestment of all income and dividends. Net of fee performance was calculated using model management fees, including for non-fee-paying accounts. The model fee is our current maximum fee of 1.5% per year for separately managed accounts which do not pay a performance-based fee. Actual advisory fees and transaction fees will vary depending on, among other things, the portfolio, account size, and activity. Fees are described in LIM’s ADV Part 2A.
On September 24, 2019, Lyons Investment Management acquired the asset management business which managed the composite presented. At the time of the acquisition LIM was affiliated with the prior firm with shared investment personnel. Performance shown prior to the acquisition date is from the prior firm. The historical performance has been linked to performance achieved at Lyons Investment Management.
The benchmark data provided was obtained from publicly available reports. LIM believes such data to be reliable but does not audit, verify, or guarantee its accuracy or completeness. When comparing the performance results to a benchmark, clients should keep in mind that: 1) Indexes are unmanaged and unavailable for direct investment. 2) Benchmark returns include reinvestment of income, but do not reflect taxes, or investment advisory or other fees that would reduce performance. 3) Performance information of benchmark indexes is included for comparison purposes only. 4) Indexes and benchmarks may not directly correlate or only partially relate to the composite.
Lyons Investment Management, Inc. (“LIM”) is an SEC registered investment adviser managing separate accounts that are fully discretionary. SEC registration does not constitute an endorsement of the firm by the Commission, nor does it indicate that the adviser has attained a particular level of skill or ability
The Morningstar RatingTM for separate accounts, commonly called the star rating, is a measure of a separate account’s risk-adjusted return, relative to other separate accounts in the same Morningstar Category. Separate accounts are rated from 1 to 5 stars, with the best performers receiving 5 stars and the worst performers receiving 1 star. Separate accounts are rated for up to three periods (three, five, and 10 years), and ratings are recalculated each quarter. The Morningstar Rating for separate accounts uses an enhanced risk-adjusted return measure, which accounts for all variations in a separate account’s monthly performance, with more emphasis on downward variation. Separate accounts are ranked against others in the same category and stars are assigned as follows: Top10% 5 stars, Next 22.5% 4 stars, Middle 35% 3 stars, Next 22.5% 2 stars, Bottom 10% 1 star.
© 2023 Morningstar, Inc. All rights reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete, or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information.
5 Star Overall RatingTM out of 158 small value funds as of 03-31-24. Compensation was provided for the display of this rating.